The difference between a covered crane loss and a six-figure write-off usually comes down to one exclusion. A 90-ton crawler crane tips on a soft-soil pad in Pasco County. A tower crane jib folds during an August squall over Brickell. A rough-terrain unit disappears from a Tampa laydown yard over a holiday weekend.
Each scenario lands on your balance sheet differently depending on how your inland marine policy was written. Crane physical damage insurance in Florida is not a commodity purchase. The state combines hurricane exposure, sandy and saturated soils, aggressive organized theft, and a construction pipeline that keeps equipment working through storm season.
In 2026, the rules have also changed. New statewide storm-securing standards now affect how insurers evaluate your hurricane claims. What follows covers overturn and upset, boom coverage, theft, vandalism, windstorm, deductibles, and the real costs you should expect. It's written for
contractors, rental houses, and
crane service companies that need coverage that pays when it counts, not coverage that only looks complete on a quote sheet.
Protecting Heavy Iron: Why Crane Physical Damage Insurance Matters in Florida
Critical Operational Risks: Overturn, Upset, and Boom Coverage
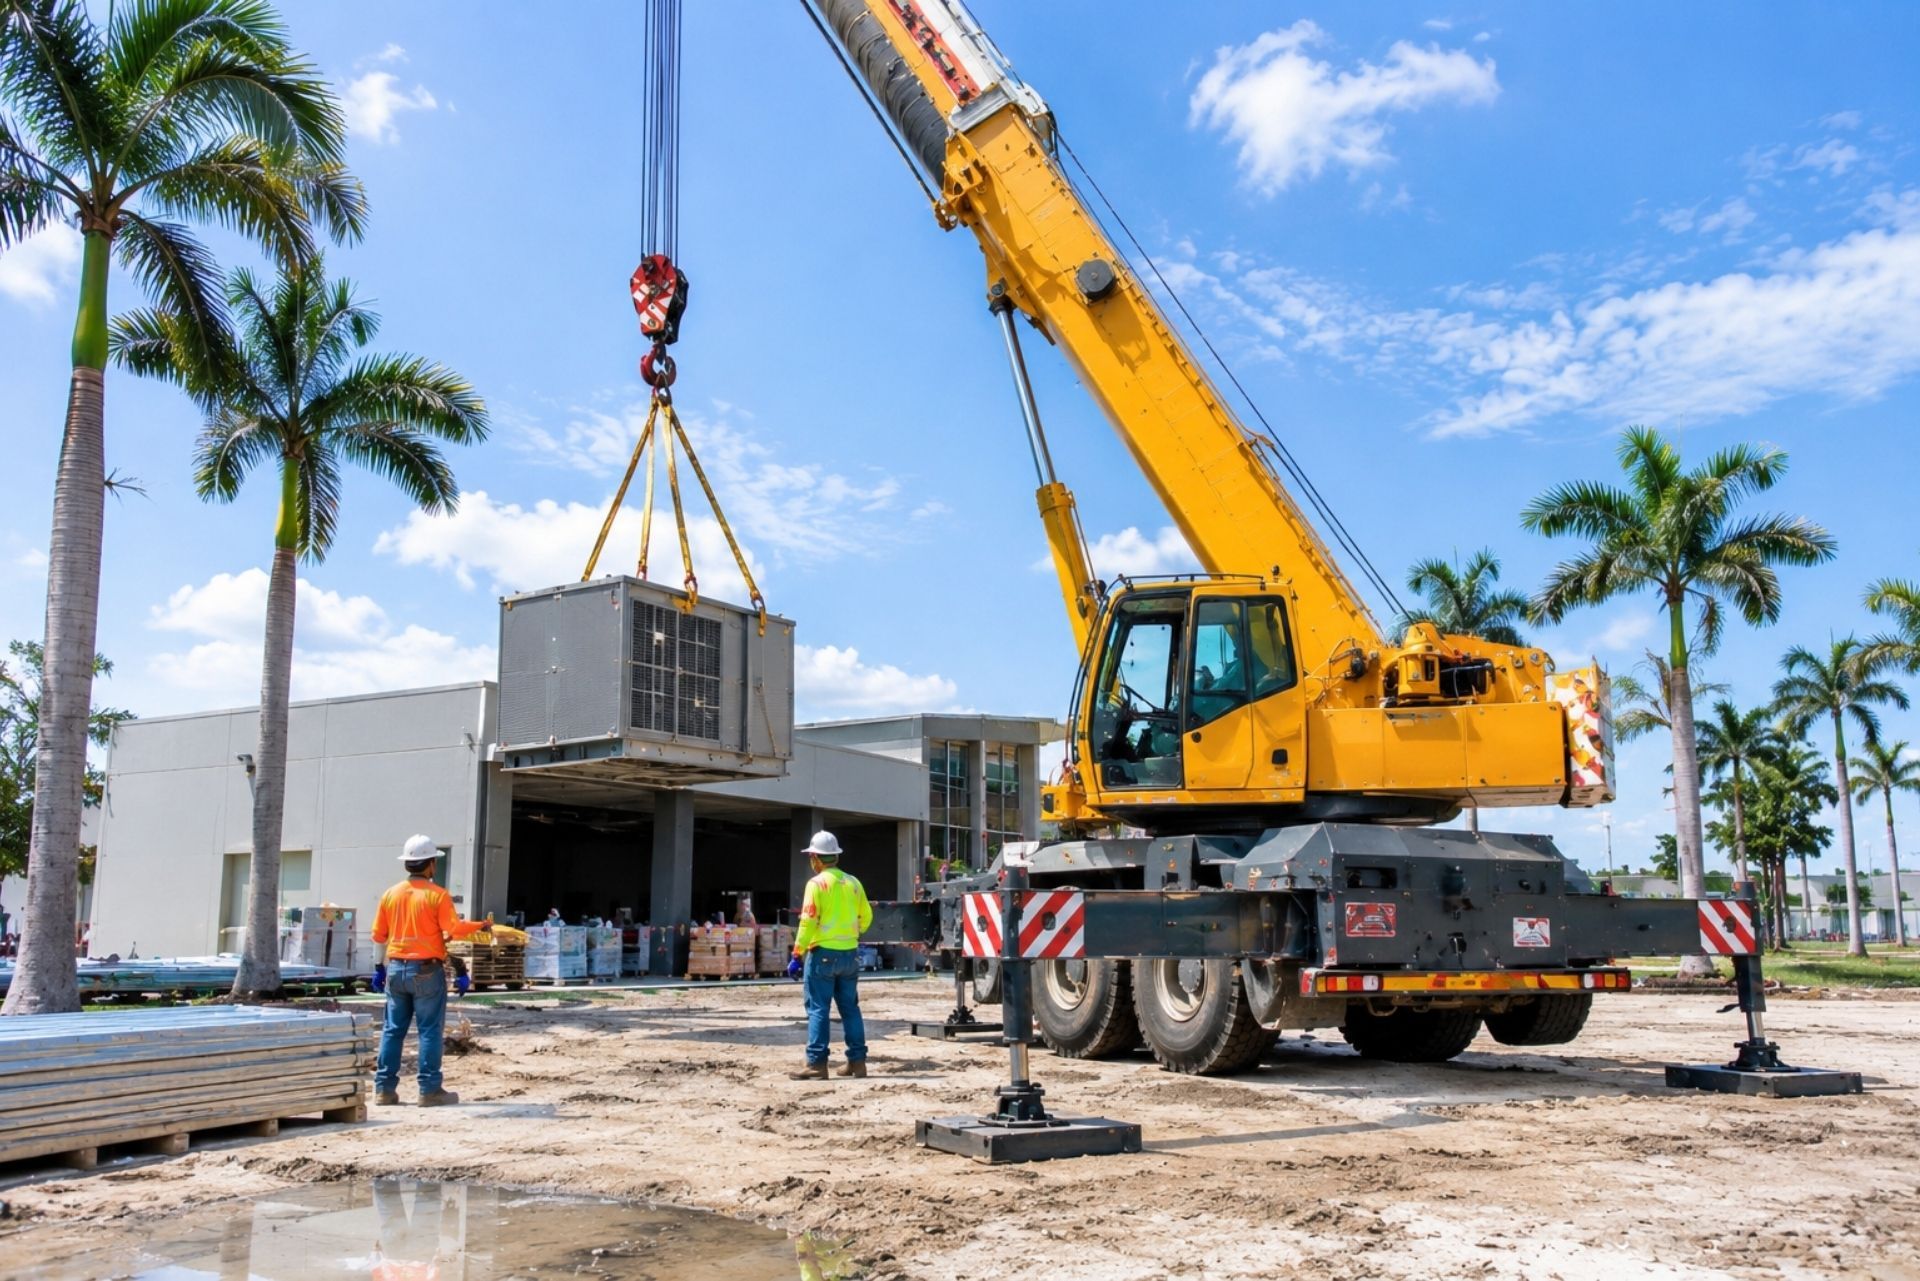
The most expensive crane claims rarely involve outside threats. They happen during the lift itself, when load charts, ground conditions, and operator judgment collide.
The Hazards of Overturn and Mechanical Upset
Overturn coverage pays when your crane tips, rolls, or falls over. Upset generally refers to a loss of stability, such as a tipping event that stops short of a full rollover but still damages outriggers, the superstructure, or the carrier.
Florida soils create a specific hazard. Outrigger pads that hold firm in the morning can sink after an afternoon thunderstorm saturates fill material. Sinkhole-prone areas around Hillsborough and Pasco Counties add another layer of risk.
The catch is that some forms exclude overturn caused by "exceeding rated capacity." Read that language carefully. If an operator misjudges a load weight by 8%, you want your policy to respond, not deny the claim as an intentional overload.
When a collapse traces back to a design or manufacturing defect, your insurer may pursue the manufacturer. The NBIS vs. Liebherr-American Inc. matter, settled in February 2025, reinforced insurers' ability to recover subrogation costs from manufacturers after product-defect collapses. Here's what that means for you: preserve inspection logs and maintenance records, because they support recovery and can help you get your deductible back.
Boom and Jib Damage: Specialized Protection Needs
Many standard equipment floaters exclude or sublimit boom damage "while in operation." That single phrase guts the coverage you need most. Boom strikes against structures, two-blocking incidents, and jib damage during erection are common claim types that some policies quietly carve out.
Ask your agent directly whether boom and jib damage during lifting is covered at full value. If the answer involves a sublimit, such as $50,000 on a boom worth $250,000, you have a gap. Boom coverage endorsements usually cost more, but they protect the component most likely to be damaged.
External Threats: Theft, Vandalism, and Florida Windstorms
Your crane is exposed even when nobody is operating it. Overnight storage, weekend shutdowns, and storm events all create losses that have nothing to do with operator error.
Theft in Florida has become organized and well funded. In May 2026, Hillsborough County authorities dismantled a $5 million organized theft ring that targeted Florida construction sites. Entire cranes are rarely driven away, but attachments, rigging, counterweights, batteries, and GPS units disappear regularly.
Vandalism has a financial driver too. Copper prices exceeded $6 per pound in early 2026, making wiring harnesses and electrical components attractive to strip. A $400 haul of copper can leave you with a $30,000 repair bill and two weeks of downtime.
Windstorm is the defining Florida exposure. Senate Bill 180 created the first statewide crane hurricane-securing standards, replacing local ordinances and requiring equipment to be secured 24 hours before impact. Under these standards, tower cranes must be placed in "weathervane mode" so they rotate freely with the wind.
Expect adjusters to ask whether you followed these protocols. Documented compliance, including timestamped photos, can be the difference between a paid claim and a dispute.
Comparing Coverage Levels and Policy Features
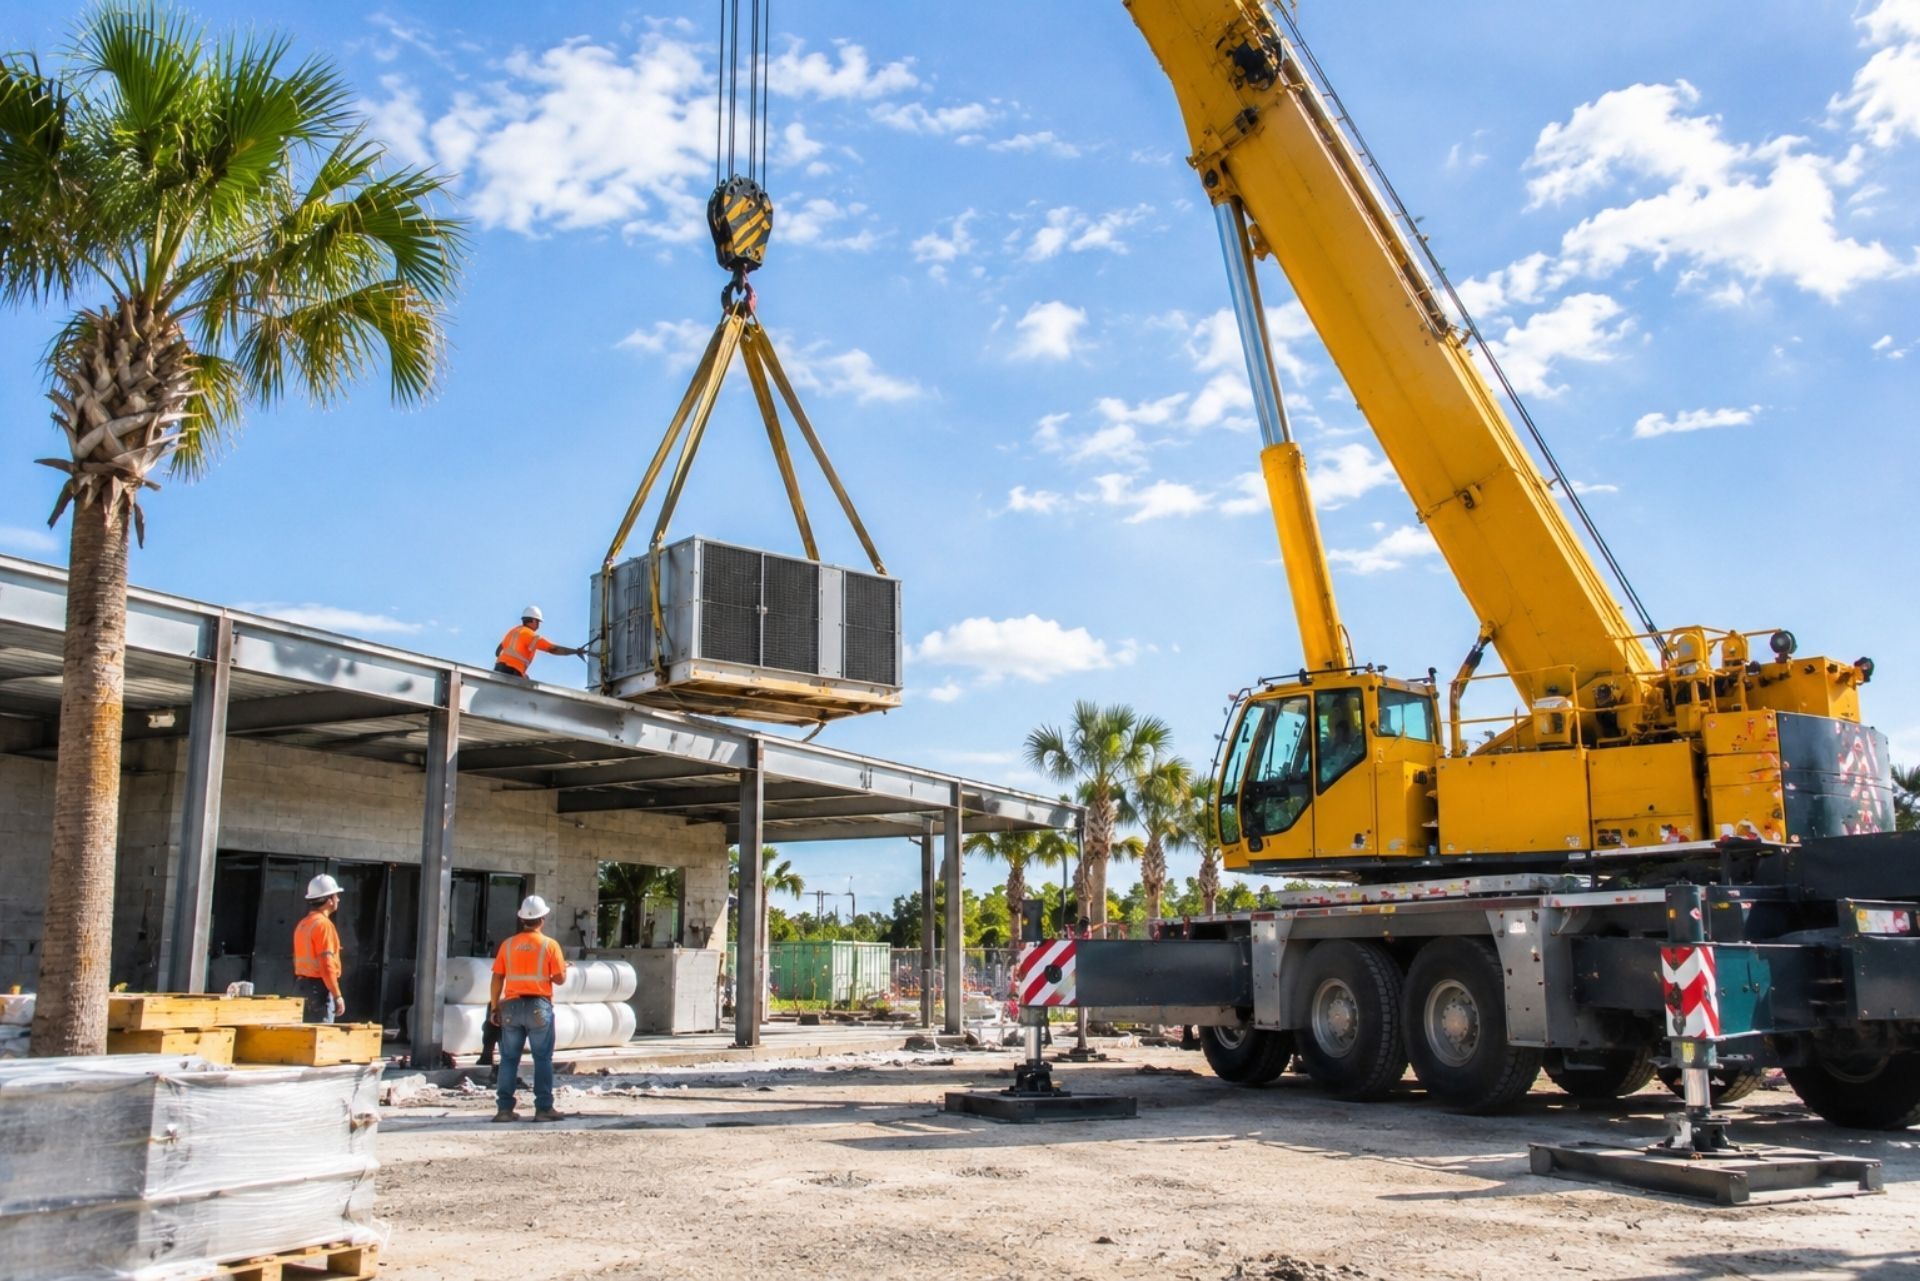
Not all crane policies are built the same. The table below shows how basic and broader forms commonly differ. Your actual terms depend on the carrier and endorsements.
| Feature | Basic Named-Peril Form | Broad Open-Peril Form |
|---|---|---|
| Overturn/upset | Often included, may exclude overload | Included, with narrower exclusions |
| Boom damage in operation | Frequently excluded or sublimited | Available by endorsement at full value |
| Theft | Covered, may require forced entry | Covered, including mysterious disappearance options |
| Vandalism | Covered | Covered |
| Windstorm | Covered, with separate named-storm deductible | Covered, with named-storm deductible |
| Valuation | Actual cash value | Replacement cost or agreed value |
| Rental reimbursement | Not included | Optional endorsement |
| Transit coverage | Limited | Broader, including over-the-road moves |
Valuation deserves special attention. Actual cash value subtracts depreciation, so a 10-year-old crane might settle far below what a comparable replacement costs. Agreed value locks in the payout amount upfront, which helps for older cranes with strong resale markets.
Rental reimbursement is often overlooked. If your crane sits in the shop for six weeks after a loss, renting a replacement could cost more than the deductible. A $50,000 or $100,000 rental reimbursement limit keeps your jobs moving.
Florida crane policies usually carry two deductible structures: a standard per-occurrence deductible and a separate windstorm or named-storm deductible. Understanding both is essential to budgeting your real costs.
How Deductible Choices Impact Your Out-of-Pocket Costs
Standard deductibles are usually a flat dollar amount. Named-storm deductibles are often a percentage of the equipment's value, which changes the math considerably.
Consider a what-if scenario. Your crawler crane is insured for $1,200,000 in Sarasota. You carry a $10,000 standard deductible and a 5% named-storm deductible.
- Boom strike on a job in March: $85,000 repair, you pay $10,000, insurer pays $75,000.
- Hurricane damage in September: $85,000 repair, your deductible is 5% of $1,200,000, which equals $60,000. The insurer pays $25,000.
Same repair bill, $50,000 difference in your out-of-pocket costs. Before you accept a percentage-based wind deductible, confirm that you can absorb it from cash reserves.
Factors That Determine Your Annual Premium
Annual premiums for heavy equipment like cranes typically run between 1% and 4% of the equipment's total value. On a $1,200,000 crane, that translates to roughly $12,000 to $48,000 per year. Where you land depends on:
- Crane type: Tower cranes and large crawlers carry different risk profiles than truck-mounted units.
- Loss history: Prior overturn or boom claims raise rates sharply.
- Operator certification: NCCCO-certified operators and documented training lower risk.
- Storage security: Fenced yards, lighting, cameras, and GPS tracking reduce theft pricing.
- Coastal exposure: Cranes working in Miami-Dade or Broward typically price higher than inland work in Polk County.
- Deductible selection: Higher deductibles reduce premiums.
There's some good news in 2026. Florida's commercial property market saw a 6.3% decrease in average premiums in Q2 2026, signaling a softening market. That said, softening doesn't apply evenly, so shop your renewal early.
Common Questions About Crane Physical Damage Policies
Does my General Liability policy cover damage to my own crane? No. General Liability covers damage you cause to others. You need a separate inland marine or contractor's equipment policy for your crane.
Is my crane covered if it's damaged while being transported? Only if your policy includes transit coverage. Confirm that over-the-road moves between job sites are covered, especially for disassembled components.
What happens if I don't secure my crane before a hurricane? Your insurer may challenge or reduce the claim. Florida's statewide standards require securing equipment 24 hours before impact, so document your compliance.
Can I insure a rented or leased crane? Yes. Rented equipment coverage protects cranes you're contractually responsible for, which most rental agreements require.
Are stolen attachments and rigging covered? Usually, if they're scheduled or fall under a tools-and-equipment limit. Check that your limit reflects what your rigging and attachments are actually worth.
Does physical damage coverage pay for normal wear and tear?
No. Wear, rust, and mechanical breakdown from age are maintenance issues, not insured losses.
Making the Right Choice for Your Fleet
Strong crane coverage comes down to specifics: full boom protection during operation, overturn language without overload loopholes, theft coverage that reflects current organized-crime activity, and a wind deductible you can actually pay. The cheapest quote rarely delivers all four.
Your next steps:
- Request the full policy form, not just the quote summary, and search for "while in operation" and "rated capacity" exclusions.
- Run the deductible math on your highest-value crane using its named-storm percentage.
- Choose agreed value for older cranes with strong resale value.
- Add rental reimbursement at $50,000 or more if downtime would stall jobs.
- Document storm compliance with timestamped photos for every 2026 hurricane prep.
- Shop your renewal 60 to 90 days early to take advantage of the softening Florida market.
A crane that's properly insured lets you bid confidently, lift confidently, and recover quickly when something goes wrong. Review your policy before storm season, not after it.
ABOUT THE AUTHOR: PAUL RAMENTOL
I am the Owner and President of Mesa Insurance Agency. I help individuals and business owners across Florida secure personal and business insurance coverage that supports their needs. My focus is on clear guidance, direct communication, and long-term support without call-center delays or confusion.
Contact Us

Personal Coverage Options
Insurance Built for Everyday Protection
Mesa Insurance Agency provides personal insurance coverage designed to support daily life. Our team reviews risks and coverage needs to help clients secure dependable protection at fair rates.
Dental & Vision Insurance
Coverage that helps manage routine dental and vision care costs.

Business Coverage Options
Insurance Built for Business Protection
Mesa Insurance Agency provides business insurance coverage that helps protect operations, employees, and property. We work with multiple carriers to offer coverage options that support daily business activities and long-term stability.
Commercial Auto Insurance
Coverage for business-owned vehicles, drivers, and accident-related liability exposure.
General Liability Insurance
Protection against third-party injury, property damage, and common business liability risks.
Professional Liability Insurance
Coverage for claims related to professional services, advice, or service errors.
Workers’ Compensation Insurance
Coverage that helps support employees with work-related injuries and medical costs.
Commercial Property Insurance
Protection for buildings, equipment, inventory, and physical business assets.
Errors & Omissions Insurance
Coverage for financial losses caused by mistakes, omissions, or service-related claims.
Industries We Serve
Serving Businesses Across Multiple Sectors
Mesa Insurance Agency works with business owners across Florida to provide insurance coverage that supports daily operations. We understand common risks faced by different industries and help clients secure reliable protection.
Construction and Trades Insurance
Coverage for job sites, vehicles, tools, and workplace risks.
Hospitality Businesses Insurance
Insurance for restaurants, bars, and service-based operations.
Retail and
Commercial Properties
Protection for storefronts, inventory, and customer-related liability.
Our Approach
Insurance Made Easy to Understand
Mesa Insurance Agency provides business insurance coverage that helps protect operations, employees, and property. We work with multiple carriers to offer coverage options that support daily business activities and long-term stability.
Insurance FAQs
Helpful Answers for Florida Clients
Support you can rely on.
What makes Mesa Insurance Agency different?
We are an independent agency with access to multiple carriers. This allows us to offer flexible coverage options.
Clients work directly with licensed agents. Service continues beyond the policy start date.
Do you offer coverage for individuals and families?
Yes. We provide personal insurance for individuals and families across Florida.
Coverage includes auto, home, health, life, and flood insurance. Our team explains each option clearly.
Do you work with small and mid-sized businesses?
Yes. We work with businesses of many sizes and industries.
Our team helps identify risks and secure appropriate coverage. Ongoing service is included.
Can I make changes to my policy later?
Yes. Policies can be updated as needs change.
We assist with coverage adjustments, additions, and removals. Clients can contact us directly for help.
Is flood insurance required in Florida?
Flood insurance is not always required, but it is strongly recommended in many areas.
Standard home insurance does not cover flood damage. Our team can review your flood risk and options.
How do I contact your office?
You can contact us by phone, email, or through our website.
Our team responds promptly during business hours. Support is always available when needed.
From the Blog
Insurance Topics That Matter
Clear answers for common questions.



Client Reviews
Trusted by Clients Across Florida
Mesa Insurance Agency is proud to serve individuals and businesses throughout Florida. Clients choose us for clear communication, responsive service, and reliable insurance support. Their feedback reflects our focus on long-term relationships and consistent service.
Contact Us