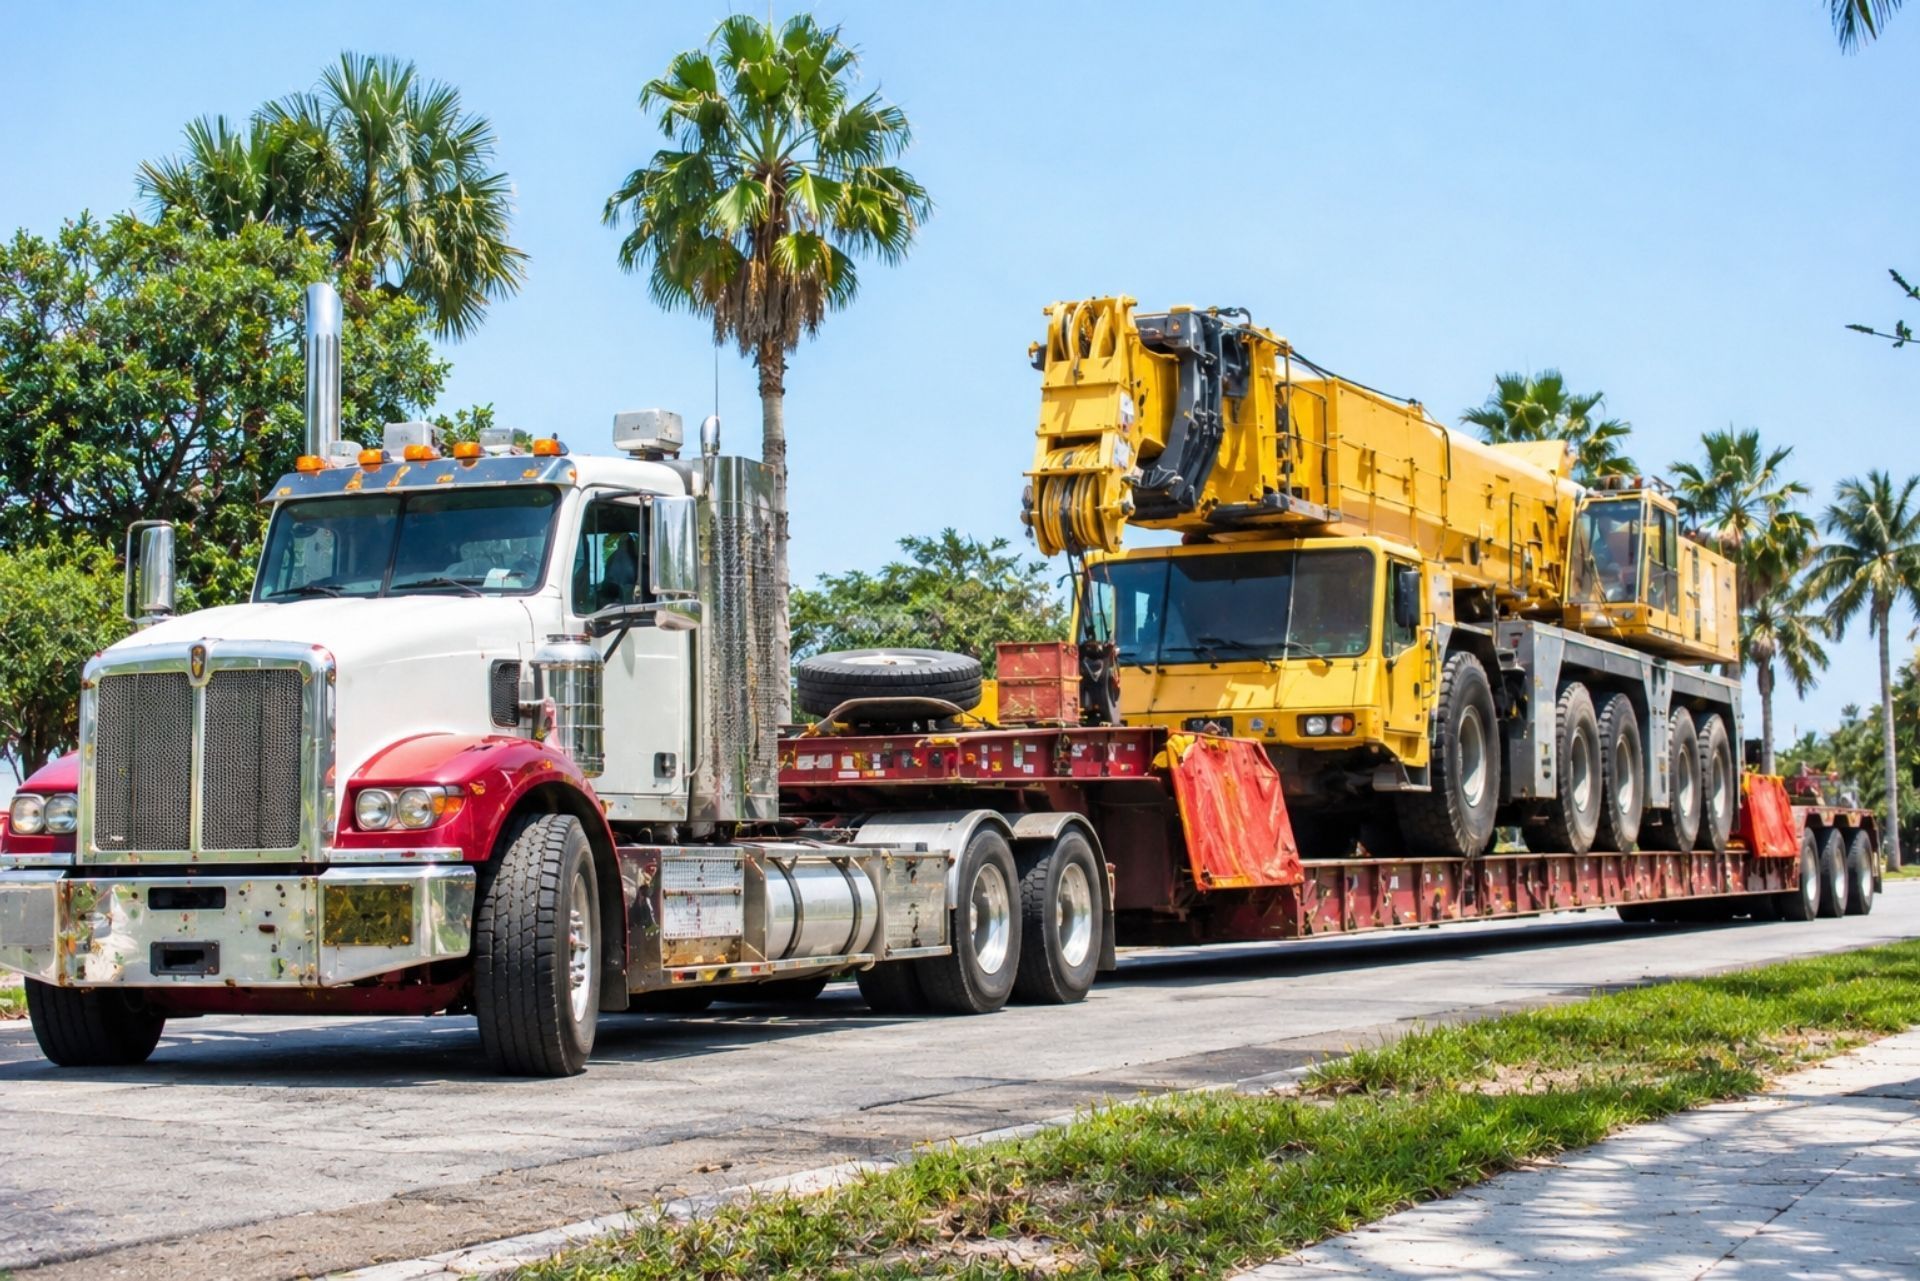
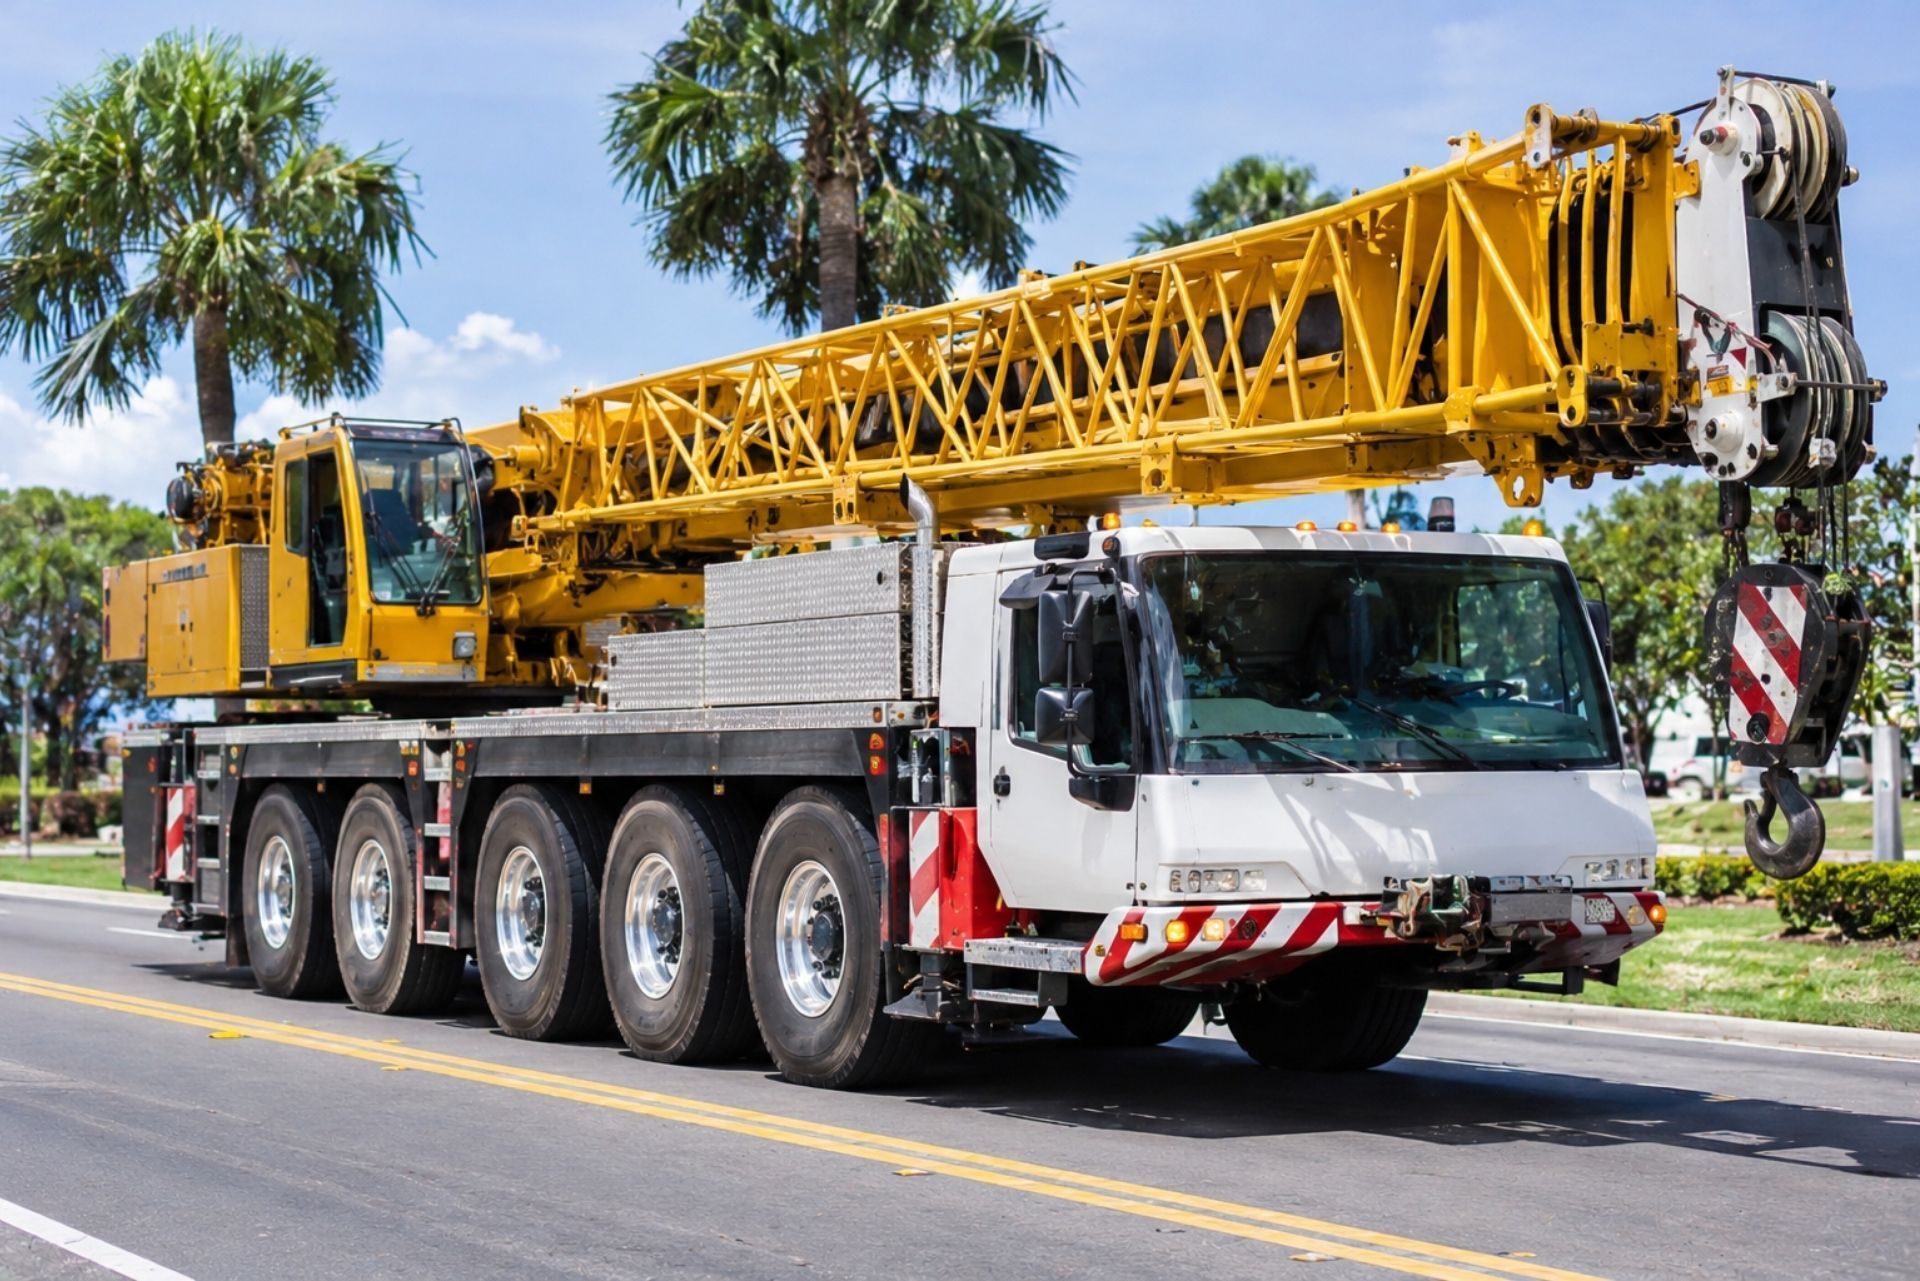
If your 60-ton hydraulic crane clips a minivan on I-4 while traveling between job sites in Orlando, the resulting claim can top seven figures before anyone calls the general contractor. Crane and rigging operators carry a different kind of road risk than any other contractor in Florida. Your vehicles are heavier, slower, and wider, and juries know they can cause catastrophic damage.
That reality shapes every part of your auto program in 2026. Florida commercial auto coverage for crane and rigging firms has to handle mobile and truck-mounted cranes, gaps from hired and non-owned vehicles, contract-driven limits, and pricing that rarely resembles a standard contractor fleet. A policy built for pickup trucks won't hold up when a boom truck tips during a pick in a Tampa parking lot.
The market itself is also changing. Carriers have exited, underwriters are asking harder questions, and general contractors keep pushing required limits higher. If you renew without understanding where your coverage starts and stops, you're likely paying for protection you won't get when it counts.
The sections below explain how these policies actually work, what limits make sense, and what drives the premium you'll see on your next quote.
Florida law puts crane owners in a uniquely exposed position. The state remains a strict vicarious liability state under the Dangerous Instrumentality Doctrine, which means you're liable for the negligence of anyone driving your crane with permission. If a subcontractor's operator causes a wreck in your truck-mounted unit, the claim lands on your policy.
The carrier side has tightened too. In late 2025, a dominant niche insurer for the crane and rigging industry exited the market after 28 years, forcing many operators to remarket their programs on short notice. Fewer specialty markets usually means stricter underwriting and less room to negotiate.
Here's what that means for you. Underwriters now want documented proof of your safety culture, not promises. As one industry broker puts it, "Everyone claims to have a strong safety program... but can you prove it when a claim occurs?" Telematics data, driver qualification files, and pre-trip inspection logs are what separate a competitive quote from a declination.
Core Coverage for Mobile and Truck-Mounted Cranes
Your commercial auto policy covers liability and damage arising from operating a vehicle on public roads. For crane fleets, the difficulty is that the same machine is both a vehicle and a piece of lifting equipment. Carriers treat those two roles very differently.
The Difference Between On-Road and Over-the-Side Coverage
Auto liability responds when your crane is being driven. Once the outriggers are down and the boom is working, most auto policies exclude the loss, and coverage shifts to your general liability or a rigging policy. This "over-the-side" gap is where many Florida operators get burned.
Consider a boom truck setting HVAC units on a Sarasota rooftop. The load swings and dents three parked cars. Your auto carrier may deny the claim because the truck wasn't in transit, while your GL carrier points to an auto exclusion. You need both policies written to dovetail, ideally with the same broker reviewing exclusion wording side by side.
Specialized Physical Damage for Heavy Equipment
Standard collision and comprehensive coverage often undervalues a crane. Insist on agreed value or stated value terms based on current replacement cost, not depreciated book value. A five-year-old all-terrain crane can still cost well over a million dollars to replace.
Ask about these provisions:
- Upset or overturn coverage for tip-overs during transit or setup
- Boom damage coverage, which some forms exclude outright
- Rental reimbursement sized to crane rental rates, not passenger car rates
- Hurricane and flood coverage for equipment parked in yards from Miami-Dade to the Panhandle
Protecting Assets with Hired and Non-Owned Auto Liability
Your rigging foreman drives his own F-250 to pick up shackles and slings from a supplier in Fort Lauderdale. He rear-ends a delivery van. His personal policy pays first, but once his limits are exhausted, the injured party comes after your company. Hired and non-owned auto liability (HNOA) covers exactly that situation.
HNOA also protects you when you rent vehicles. That includes a pickup rented for a Jacksonville project, a pilot car hired for an oversize move, or a short-term flatbed used to haul matting. Without it, your business is exposed for vehicles you don't own but are still responsible for.
The cost is modest. Florida contractors typically pay between $150 and $400 per year for HNOA coverage, which makes it one of the cheapest coverage lines on your entire program. One thing to keep in mind: HNOA is liability-only. It won't repair the rented truck itself, so you'll need hired physical damage coverage or the rental company's damage waiver for that exposure.
A common mistake is assuming your umbrella policy picks up HNOA automatically. Most umbrellas only sit over coverages listed on your underlying schedule, so confirm HNOA appears there.
Florida Insurance Requirements vs. Industry Standards
Florida's legal requirements and what the crane industry actually expects are far apart. Meeting the state minimum keeps you legal on the road. It won't get you onto most commercial job sites.
State law ties minimum liability to vehicle weight. Under a 2026 amendment, Florida requires minimums ranging from $50,000 for vehicles over 26,000 lbs to $300,000 for those over 44,000 lbs. Oversize moves add another layer: the FDOT permit system lets you self-issue trip permits for mobile cranes exceeding legal dimensions up to 200,000 pounds, provided your insurance meets the weight-based minimums.
Comparing State Minimums to Recommended High Limits
General contractors set the real bar. Many require crane operators to carry $5,000,000 in excess or umbrella coverage, and $10,000,000 or more is common on industrial plants, ports, hospitals, and other mission-critical infrastructure.
| Requirement | Typical Limit | Who Sets It |
|---|---|---|
| State minimum, over 26,000 lbs | $50,000 | Florida law |
| State minimum, over 44,000 lbs | $300,000 | Florida law |
| Primary auto liability (recommended) | $1,000,000 CSL | Industry practice |
| Commercial GC projects | $5,000,000 excess | Contract terms |
| Industrial or infrastructure | $10,000,000+ excess | Contract terms |
For most Florida crane operators, $1,000,000 primary auto liability paired with at least $5,000,000 in excess coverage is the practical starting point.
Factors Influencing Crane Insurance Costs in Florida
Expect to pay more than contractors in other states. Commercial auto premiums for Florida heavy construction fleets run 40 to 60 percent higher than the national average, with heavy trucks requiring $5,000 to $18,000 or more in annual premium per vehicle.
There is some relief on the broader market. Florida's insurance commissioner announced that the state's top five auto insurance groups indicated an average rate decrease of 8 percent for the year, following the 2023 tort reforms. The catch is that those figures reflect mainstream auto carriers, and specialty crane markets don't always follow the same trend.
Your premium will mostly depend on:
- Vehicle weight and value, especially all-terrain and large truck-mounted units
- Radius of operation, since statewide travel costs more than local work
- Driver records, including CDL violations and years operating cranes
- Loss history, typically the past three to five years
- Territory, with South Florida counties rating higher than rural areas
- Safety documentation, such as telematics, cameras, and written lift plans
Here's a what-if. Suppose you run eight heavy units averaging $11,000 each, for $88,000 in auto premium. A $250,000 at-fault claim with a $25,000 deductible costs you $25,000 directly, and a typical surcharge of 15 to 25 percent at renewal could add another $13,000 to $22,000 a year for three years. That's the real price of one preventable wreck.
Common Questions About Crane and Rigging Auto Policies
Does my auto policy cover a crane while it's lifting? Usually not. Most auto policies stop responding once the crane is set up and working, so you need general liability or a rigging policy to cover that exposure.
Do I need HNOA if all my trucks are company-owned? Yes, in most cases. Employees running errands in personal vehicles or rented trucks create liability that your owned-auto coverage won't touch.
Will the state minimum satisfy my general contractor? Almost never. Most GCs require $1,000,000 primary auto liability plus several million in excess coverage.
Am I liable if a subcontractor wrecks my crane? Under Florida's Dangerous Instrumentality Doctrine, you generally are liable if they were driving with your permission.
Why did my renewal jump when Florida auto rates are falling? Statewide rate decreases mostly reflect personal and standard commercial carriers. Specialty crane markets price on their own capacity and losses, and capacity tightened after a major insurer left in 2025.
Can telematics lower my premium? It often helps. Underwriters give credit when you can show documented driving behavior and corrective action.
Securing the Right Protection for Your Fleet
A strong crane auto program in 2026 does three things well. It covers your units on the road at true replacement value, it coordinates with your GL and rigging policies so over-the-side losses don't fall through, and it carries limits high enough to win the jobs you want.
Florida's vicarious liability rules and a thinner specialty market make shortcuts expensive. Your next steps:
- Schedule every crane at agreed or stated replacement value
- Have your broker compare auto and GL exclusions to close the over-the-side gap
- Add HNOA and hired physical damage, then confirm both sit under your umbrella
- Carry at least $1,000,000 primary and $5,000,000 excess, more for industrial work
- Build a documented safety file with telematics, driver records, and lift plans
- Start remarketing 90 to 120 days before renewal
The operators who get the best terms aren't the ones with the cleanest sales pitch. They're the ones who can prove their safety program on paper before a claim ever happens.
ABOUT THE AUTHOR: PAUL RAMENTOL
I am the Owner and President of Mesa Insurance Agency. I help individuals and business owners across Florida secure personal and business insurance coverage that supports their needs. My focus is on clear guidance, direct communication, and long-term support without call-center delays or confusion.
Contact Us

Personal Coverage Options
Insurance Built for Everyday Protection
Mesa Insurance Agency provides personal insurance coverage designed to support daily life. Our team reviews risks and coverage needs to help clients secure dependable protection at fair rates.
Dental & Vision Insurance
Coverage that helps manage routine dental and vision care costs.

Business Coverage Options
Insurance Built for Business Protection
Mesa Insurance Agency provides business insurance coverage that helps protect operations, employees, and property. We work with multiple carriers to offer coverage options that support daily business activities and long-term stability.
Commercial Auto Insurance
Coverage for business-owned vehicles, drivers, and accident-related liability exposure.
General Liability Insurance
Protection against third-party injury, property damage, and common business liability risks.
Professional Liability Insurance
Coverage for claims related to professional services, advice, or service errors.
Workers’ Compensation Insurance
Coverage that helps support employees with work-related injuries and medical costs.
Commercial Property Insurance
Protection for buildings, equipment, inventory, and physical business assets.
Errors & Omissions Insurance
Coverage for financial losses caused by mistakes, omissions, or service-related claims.
Industries We Serve
Serving Businesses Across Multiple Sectors
Mesa Insurance Agency works with business owners across Florida to provide insurance coverage that supports daily operations. We understand common risks faced by different industries and help clients secure reliable protection.
Construction and Trades Insurance
Coverage for job sites, vehicles, tools, and workplace risks.
Hospitality Businesses Insurance
Insurance for restaurants, bars, and service-based operations.
Retail and
Commercial Properties
Protection for storefronts, inventory, and customer-related liability.
Our Approach
Insurance Made Easy to Understand
Mesa Insurance Agency provides business insurance coverage that helps protect operations, employees, and property. We work with multiple carriers to offer coverage options that support daily business activities and long-term stability.
Insurance FAQs
Helpful Answers for Florida Clients
Support you can rely on.
What makes Mesa Insurance Agency different?
We are an independent agency with access to multiple carriers. This allows us to offer flexible coverage options.
Clients work directly with licensed agents. Service continues beyond the policy start date.
Do you offer coverage for individuals and families?
Yes. We provide personal insurance for individuals and families across Florida.
Coverage includes auto, home, health, life, and flood insurance. Our team explains each option clearly.
Do you work with small and mid-sized businesses?
Yes. We work with businesses of many sizes and industries.
Our team helps identify risks and secure appropriate coverage. Ongoing service is included.
Can I make changes to my policy later?
Yes. Policies can be updated as needs change.
We assist with coverage adjustments, additions, and removals. Clients can contact us directly for help.
Is flood insurance required in Florida?
Flood insurance is not always required, but it is strongly recommended in many areas.
Standard home insurance does not cover flood damage. Our team can review your flood risk and options.
How do I contact your office?
You can contact us by phone, email, or through our website.
Our team responds promptly during business hours. Support is always available when needed.
From the Blog
Insurance Topics That Matter
Clear answers for common questions.



Client Reviews
Trusted by Clients Across Florida
Mesa Insurance Agency is proud to serve individuals and businesses throughout Florida. Clients choose us for clear communication, responsive service, and reliable insurance support. Their feedback reflects our focus on long-term relationships and consistent service.
Contact Us