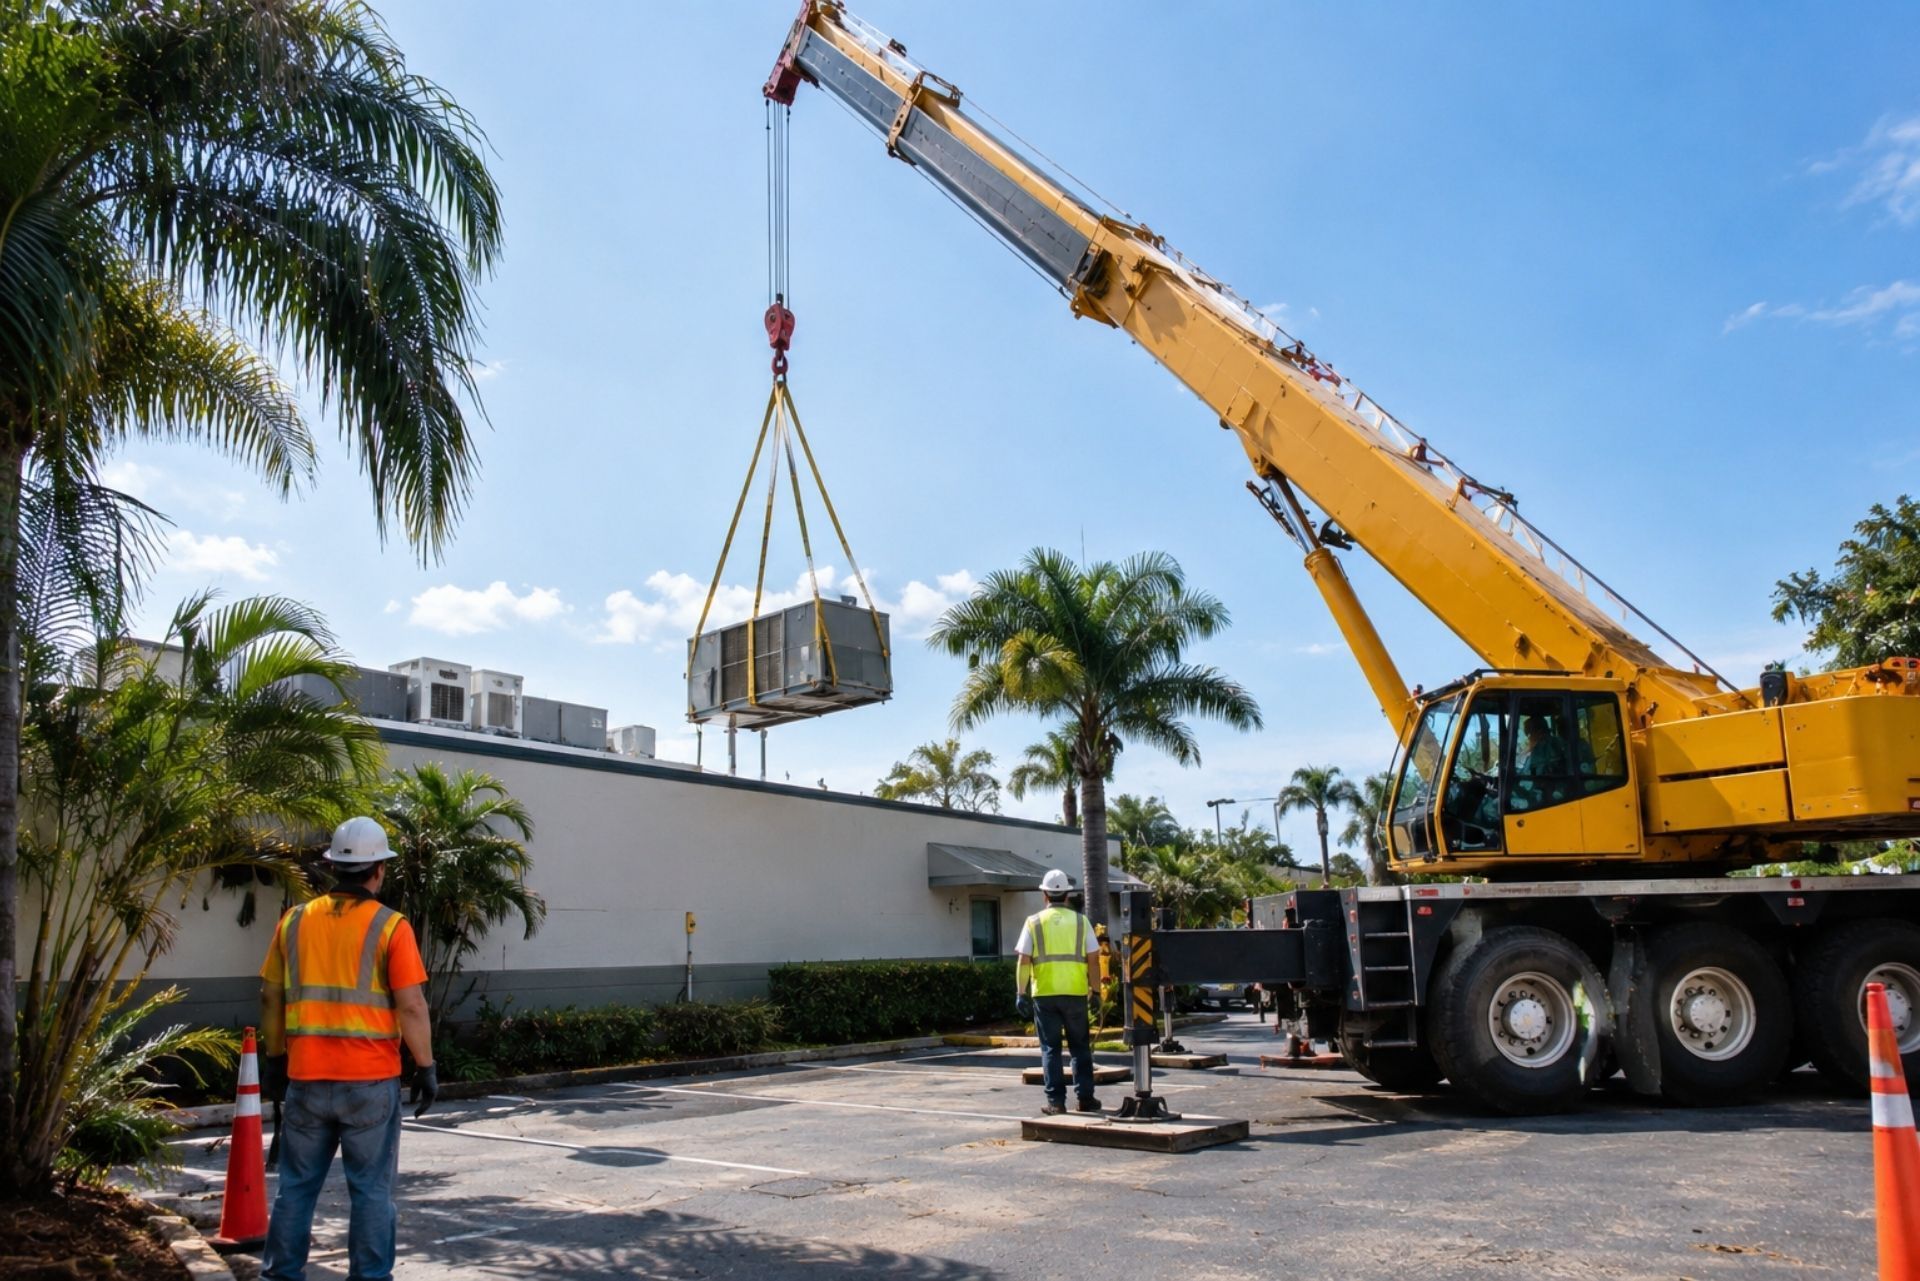
A 90-ton crane tips while setting HVAC units on a Tampa rooftop. The load lands on a parked car, the boom clips a neighboring building, and the client's rooftop chiller, worth more than your truck, is now scrap. Three different insurance policies might respond to that single afternoon, and if you bought the wrong mix, none of them will.
That is the reality of crane and rigging insurance in Florida for 2026. Your operation faces a stacked set of exposures: the equipment itself, the property you lift, the people on your crew, the vehicles hauling gear down I-4, and the third parties standing nearby. Each of those risks belongs to a specific policy, and the gaps between policies are where most denied claims live.
This guide breaks down how riggers liability, crane physical damage, general liability,
commercial auto, and workers' compensation fit together, plus what Florida contractors realistically pay. You'll also see where claims commonly fall through the cracks and how to structure a program that holds up when an adjuster starts asking questions.
The Risk Landscape for Florida Crane and Rigging Operations
Florida adds weather risk that most states simply don't carry. Hurricane Milton in October 2024 produced estimated insured losses between $20 billion and $60 billion, and underwriters still price crane fleets with that storm in mind. When a tower crane collapses in high wind, the claim can involve the crane, the building under construction, adjacent properties, and injured bystanders all at once.
The state responded with new rules. Florida's SB 180 sets uniform statewide standards requiring hoisting equipment to be secured 24 hours before anticipated hurricane impacts. Tower cranes must also be placed in "weathervane mode" so they rotate freely with the wind. The legislature passed this 24-hour rule for securing hoisting equipment alongside debris removal and rebuilding measures.
This matters because compliance now affects claims. If your crane comes down during a storm and you can't document that it was secured on time, expect a carrier to scrutinize the loss closely. Keep dated photos, signed checklists, and operator logs for every storm prep.
Beyond weather, Florida rigging firms face:
- Dropped loads on job sites in dense areas like Miami-Dade and downtown Orlando
- Setup failures from soft, sandy soil and high water tables under outriggers
- Transit accidents moving oversize equipment on congested highways
- Aggregation exposure when expensive machinery is stored in one yard
Essential Insurance Coverages for the Rigging Industry
No single policy covers a crane company. You need a coordinated program where each policy picks up where another stops.
General Liability and Riggers Liability Explained
General liability (GL) covers bodily injury and property damage you cause to third parties. If a passing pedestrian is struck by debris or your outrigger cracks a client's driveway, GL responds. The catch is that most GL policies exclude damage to property in your "care, custody, or control."
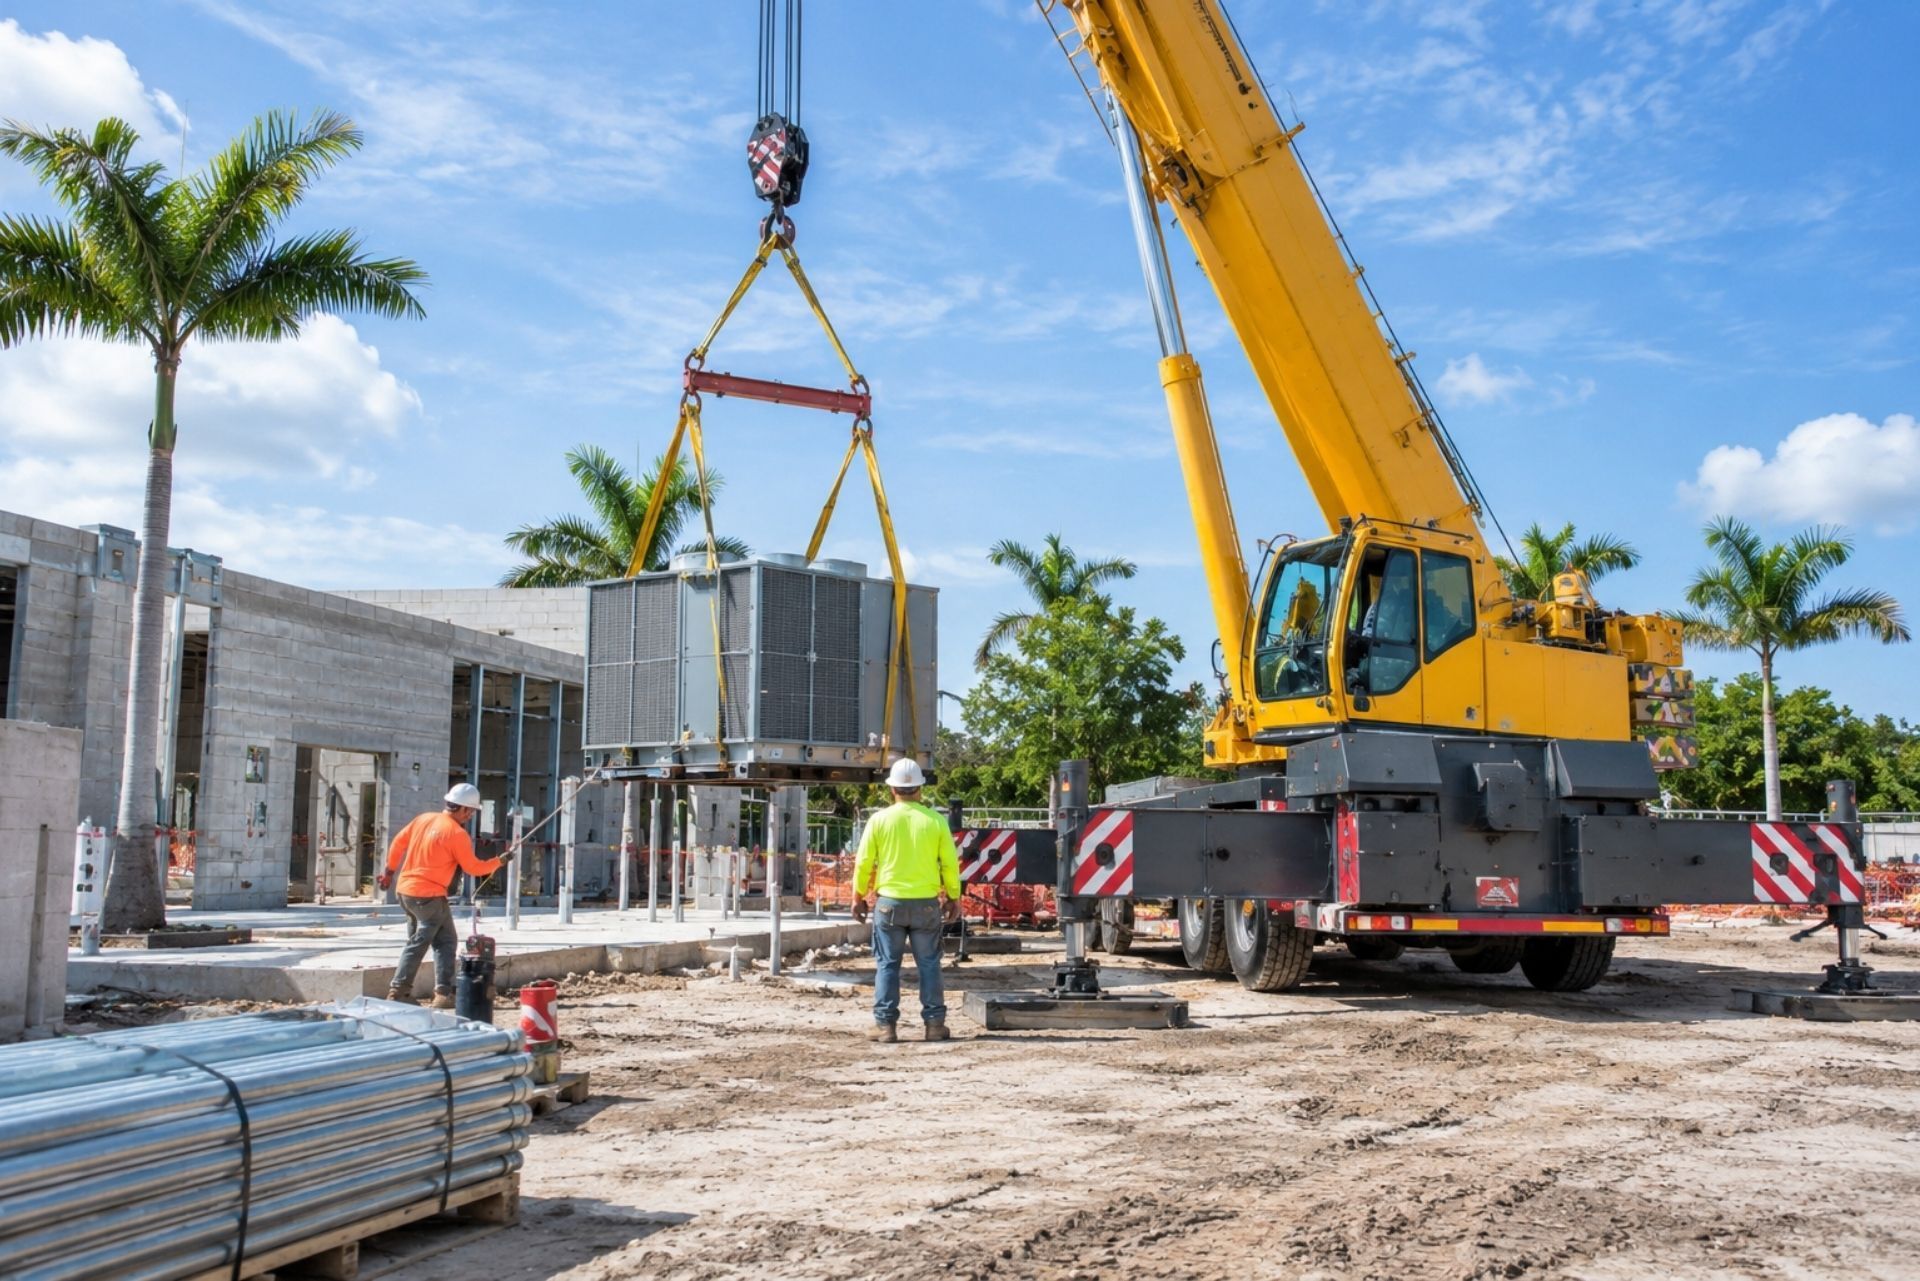
That exclusion is the whole reason riggers liability exists. When you're lifting a client's generator, transformer, or precast panel, that item is in your custody. Drop it, and GL usually won't pay. Riggers liability covers damage to the property you're hoisting, moving, or rigging.
A common client mistake: buying riggers liability limits based on average jobs. If you set data center equipment or medical imaging machines even twice a year, your limit should match the most valuable load you'll ever lift, not the typical one.
Crane Physical Damage and Inland Marine
Your cranes are covered under an inland marine policy, often called a contractor's equipment floater. It pays to repair or replace the crane after an upset, collision, theft, fire, or windstorm. Read the overturn and boom-failure language carefully, since some forms limit coverage for mechanical breakdown or operator error.
Here's what that means for you right now: the inland marine market is in a buyer-friendly cycle with increased carrier capacity, so you can often negotiate higher limits and broader terms than you could a few years ago. That said, carriers are watching aggregation risk, where millions in machinery sits in a single location. If you park your fleet in one yard, expect questions about per-location limits.
Commercial Auto and Workers' Compensation Requirements
Commercial auto covers trucks, tractors, and support vehicles on the road. Mobile cranes that travel public roads may need to be scheduled on the auto policy, while the crane's lifting operations fall under GL and inland marine. Confirm with your agent which policy covers a truck-mounted crane while it's working versus driving.
Workers' compensation pays medical bills and lost wages when a crew member gets hurt. Florida applies stricter employee thresholds to construction businesses than to most other industries, so assume you need coverage from your first hire. Riggers and operators carry high classification rates, which makes payroll accuracy critical at audit time.
Comparing Coverage: General Liability vs. Riggers Liability
Many contractors assume their GL policy covers everything that happens on a lift. It doesn't. The table below shows where each policy responds.
| Scenario | General Liability | Riggers Liability |
|---|---|---|
| Load falls on a bystander's car | Covered | Not covered |
| Client's HVAC unit dropped during lift | Usually excluded | Covered |
| Pedestrian injured by swinging load | Covered | Not covered |
| Generator damaged while being set | Usually excluded | Covered |
| Damage to neighboring building | Covered | Not covered |
| Your own crane damaged | Not covered | Not covered (inland marine) |
Consider a what-if. You're setting a $400,000 transformer at a Sarasota substation project. A sling fails, the transformer drops, and it also crushes a parked pickup. Your GL policy pays for the pickup. The transformer, which was in your care, falls under riggers liability. If you carry only $250,000 in riggers coverage, you're personally on the hook for the remaining $150,000, plus any deductible.
One thing to keep in mind: riggers liability comes in two forms. "Legal liability" pays only when you're found negligent. "Direct damage" pays regardless of fault. Direct damage costs more, but it preserves client relationships because you're not arguing about blame while the customer waits for a replacement unit.
Factors Influencing Crane Insurance Costs in Florida
A typical Florida crane and rigging company pays combined annual premiums between $35,000 and $70,000 across all policies. Where you land in that range depends on several factors.
Crane physical damage, written as inland marine, generally runs between 1% and 3% of total equipment value. For a fleet valued at $2 million, that's roughly $20,000 to $60,000 a year for equipment coverage alone. Specialized on-hook coverage for towing and transport typically adds $300 to $1,500 per vehicle annually.
What pushes your rate higher or lower:
- Crane capacity and type. Tower cranes and high-tonnage units cost more to insure than boom trucks.
- Loss history. One dropped-load claim can follow you for three to five years of renewals.
- Operator certification. Documented NCCCO credentials and training records help.
- Storage practices. Spreading equipment across multiple secured yards addresses aggregation concerns.
- Coastal exposure. Operations concentrated in Miami-Dade, Broward, or the Gulf Coast face higher windstorm pricing.
- Payroll and classification. Workers' comp swings heavily based on how accurately you classify operators versus ground crew.
- Work type. Petrochemical, utility, and high-rise work rate higher than residential tree or HVAC lifts.
The soft inland marine market gives you room to push back. Get competing quotes, and ask carriers to explain any rate above the 1% to 3% range.
Common Questions About Crane and Rigging Insurance
Does my general liability cover a load I drop? Usually not, if the load belongs to your client and is in your custody. You need riggers liability for that.
How much riggers liability should I carry? Match your limit to the most valuable item you'll realistically lift in a year. Many Florida contractors start at $500,000 and move to $1 million or more for industrial work.
Is my crane covered by commercial auto? Auto covers the crane while driving on public roads if it's scheduled on the policy. Damage to the crane itself during lifting falls under inland marine.
Do I need workers' comp if I only have a few employees? Yes. Florida holds construction businesses to stricter standards than other industries, so plan on carrying it from your first employee.
Will a hurricane claim be denied if I didn't secure my crane? Carriers can scrutinize claims when equipment wasn't secured under the 24-hour rule. Document every storm prep to protect yourself.
Can I lower my premium without cutting coverage?
Yes. Spread equipment across locations, maintain operator certifications, and shop the soft inland marine market at renewal.
Securing the Right Policy for Your Fleet
The strongest crane programs treat each policy as one piece of a coordinated system. General liability handles third parties, riggers liability protects the loads you lift, inland marine covers your equipment, commercial auto handles the road, and workers' comp protects your crew. Gaps between them are where Florida contractors lose money, especially after storms.
Your next steps for 2026:
- Audit your riggers limit against your highest-value lift from the past year.
- Confirm care, custody, or control language in your GL policy so you know exactly what's excluded.
- Build a hurricane prep file with dated photos and checklists showing 24-hour compliance and weathervane mode.
- Review storage locations and request per-location limits that reflect aggregation exposure.
- Shop inland marine now while carrier capacity favors buyers.
- Verify payroll classifications before your workers' comp audit.
Getting crane and rigging coverage right in Florida takes more than buying policies. It takes knowing which one pays when something drops.
ABOUT THE AUTHOR: PAUL RAMENTOL
I am the Owner and President of Mesa Insurance Agency. I help individuals and business owners across Florida secure personal and business insurance coverage that supports their needs. My focus is on clear guidance, direct communication, and long-term support without call-center delays or confusion.
Contact Us

Personal Coverage Options
Insurance Built for Everyday Protection
Mesa Insurance Agency provides personal insurance coverage designed to support daily life. Our team reviews risks and coverage needs to help clients secure dependable protection at fair rates.
Dental & Vision Insurance
Coverage that helps manage routine dental and vision care costs.

Business Coverage Options
Insurance Built for Business Protection
Mesa Insurance Agency provides business insurance coverage that helps protect operations, employees, and property. We work with multiple carriers to offer coverage options that support daily business activities and long-term stability.
Commercial Auto Insurance
Coverage for business-owned vehicles, drivers, and accident-related liability exposure.
General Liability Insurance
Protection against third-party injury, property damage, and common business liability risks.
Professional Liability Insurance
Coverage for claims related to professional services, advice, or service errors.
Workers’ Compensation Insurance
Coverage that helps support employees with work-related injuries and medical costs.
Commercial Property Insurance
Protection for buildings, equipment, inventory, and physical business assets.
Errors & Omissions Insurance
Coverage for financial losses caused by mistakes, omissions, or service-related claims.
Industries We Serve
Serving Businesses Across Multiple Sectors
Mesa Insurance Agency works with business owners across Florida to provide insurance coverage that supports daily operations. We understand common risks faced by different industries and help clients secure reliable protection.
Construction and Trades Insurance
Coverage for job sites, vehicles, tools, and workplace risks.
Hospitality Businesses Insurance
Insurance for restaurants, bars, and service-based operations.
Retail and
Commercial Properties
Protection for storefronts, inventory, and customer-related liability.
Our Approach
Insurance Made Easy to Understand
Mesa Insurance Agency provides business insurance coverage that helps protect operations, employees, and property. We work with multiple carriers to offer coverage options that support daily business activities and long-term stability.
Insurance FAQs
Helpful Answers for Florida Clients
Support you can rely on.
What makes Mesa Insurance Agency different?
We are an independent agency with access to multiple carriers. This allows us to offer flexible coverage options.
Clients work directly with licensed agents. Service continues beyond the policy start date.
Do you offer coverage for individuals and families?
Yes. We provide personal insurance for individuals and families across Florida.
Coverage includes auto, home, health, life, and flood insurance. Our team explains each option clearly.
Do you work with small and mid-sized businesses?
Yes. We work with businesses of many sizes and industries.
Our team helps identify risks and secure appropriate coverage. Ongoing service is included.
Can I make changes to my policy later?
Yes. Policies can be updated as needs change.
We assist with coverage adjustments, additions, and removals. Clients can contact us directly for help.
Is flood insurance required in Florida?
Flood insurance is not always required, but it is strongly recommended in many areas.
Standard home insurance does not cover flood damage. Our team can review your flood risk and options.
How do I contact your office?
You can contact us by phone, email, or through our website.
Our team responds promptly during business hours. Support is always available when needed.
From the Blog
Insurance Topics That Matter
Clear answers for common questions.



Client Reviews
Trusted by Clients Across Florida
Mesa Insurance Agency is proud to serve individuals and businesses throughout Florida. Clients choose us for clear communication, responsive service, and reliable insurance support. Their feedback reflects our focus on long-term relationships and consistent service.
Contact Us